• Skip to content
  • Skip to primary sidebar

liskow_lewis_white_new

future-focused

  • Team
  • Practices
  • Insights
  • Blogs
    • Energy Law Blog
    • Gulf Coast Business Law Blog
    • Maritime Law Blog
    • Louisiana Industrial Insights Hub

Blogs

Residential Real Estate Rule – FinCen Reporting Starting March 1st

March 3, 20266 minute read

Featured Image

In 2024, the U.S. Department of the Treasury’s Financial Crimes Enforcement Network (“FinCEN”) issued the Anti-Money Laundering Regulations for Residential Real Estate Transfers (the “RRE Rule”) requiring the reporting of non-financed transfers of residential real property to certain legal entity and trust transferees. The RRE Rule seeks to “curtail the ability of illicit actors to anonymously launder illicit proceeds through transfers of residential real property, which threatens U.S. economic and national security.” Reporting under the RRE Rule began on March 1, 2026.

What Transfers Are Affected?

The RRE Rule applies if all the following conditions are met and an exception does not apply:

  • the property is Residential Real Property

  • the transaction is a non-financed transfer (i.e., the transfer does not involve an extension of credit to all transferees secured by the transferred Residential Real Property and extended by a financial institution having both an obligation to maintain an anti-money laundering program and an obligation to report suspicious transactions under the RRE Rule)

  • the property is transferred to a qualifying legal entity (such as an association, corporation, estate, limited liability company, or partnership) or qualifying trust

“Residential Real Property” means property located in the United States and is (1) real property containing a structure designed principally for occupancy by one to four families; (2) land on which the transferee intends to build a structure designed principally for occupancy by one to four families; (3) a unit designed principally for occupancy by one to four families within a structure on land; or (4) shares in a cooperative housing corporation.  In certain instances, apartments, condominiums, timeshares, undeveloped land, and vacant lots may be considered Residential Real Property.

Who Must Report?

Real estate professionals involved in the transaction of the Residential Real Property are required to file the reports, home buyers are not required to file unless they are involved in the functions listed below. There is only one reporting person for a transaction of Residential Real Property, the first person performing one of the following functions is required to report:

  1. the person listed as the closing or settlement agent on the closing or settlement statement for the transfer;

  2. if no person described above is involved in the transfer, then the person that prepares the closing or settlement statement for the transfer;

  3. if no person described above is involved in the transfer, then the person that files with the recordation office the deed or other instrument that transfers ownership of the Residential Real Property;

  4. if no person described above is involved in the transfer, then the person that underwrites an owner’s title insurance policy for the transferee with respect to the transferred Residential Real Property;

  5. if no person described above is involved in the transfer, then the person that disburses in any form, including from an escrow account, trust account, or lawyers’ trust account, the greatest amount of funds in connection with the Residential Real Property transfer;

  6. if no person described above is involved in the transfer, then the person that provides an evaluation of the status of the title; or

  7. if no person described above is involved in the transfer, then the person that prepares the deed or, if no deed is involved, any other legal instrument that transfers ownership of the Residential Real Property, including, with respect to shares in a cooperative housing corporation, the person who prepares the stock certificate.

The persons described above may enter into an agreement to designate which person will be the reporting person with respect to the reportable transfer. The person designated by such agreement shall be treated as the reporting person with respect to only a specific reportable transfer. If the above persons decide to use designation agreements, a separate agreement is required for each reportable transfer.

When is the Deadline for the Real Estate Report?

The Real Estate Report must be filed by the later date of either the final day of the month following the month in which closing occurred or thirty calendar days after the date of closing.

What Is Reported?

FinCEN requires the submittal of the Real Estate Report. The Real Estate Report includes the following information (as applicable):

  • reporting person – full legal name, category of reporting person (items no. 1 through 7 above), and street address of principal place of business in the United States

  • transferee entity – full legal name, trade name or “doing business as” name, if any, street address of principal place of business, and Internal Revenue Service (“IRS”) tax identification number (if none, foreign jurisdiction tax identification number or, if none, foreign jurisdiction entity registration number)

    • beneficial owner (if any) – full legal name, date of birth, residential street address, citizenship, and IRS tax identification number (if none, foreign jurisdiction tax identification number or non-expired passport number)

  • transferee trust – full legal name (full title of the agreement establishing the trust), date trust instrument was executed, IRS tax identification number (or, if none, foreign jurisdiction tax identification number), and whether the trust is revocable

    • trustee – full legal name, trade name or “doing business as” name, if any, street address of principal place of business, and IRS tax identification number (if none, foreign jurisdiction tax identification number or, if none, foreign jurisdiction entity registration number)

      • A trustee will be treated as a beneficial owner of a trust and must also report the information below

    • beneficial owner (if any) – full legal name, date of birth, residential street address, citizenship, and IRS tax identification number (if none, foreign jurisdiction tax identification number or non-expired passport number), and the category of beneficial owner

  • transferor individual – full legal name, date of birth, residential street address, and IRS tax identification number (if none, foreign jurisdiction tax identification number or non-expired passport number)

  • transferor entity – full legal name, trade name or “doing business as” name, if any, street address of principal place of business, and IRS tax identification number (if none, foreign jurisdiction tax identification number or, if none, foreign jurisdiction entity registration number)

  • transferor trust – full legal name (full title of the agreement establishing the trust), date trust instrument was executed, and IRS tax identification number (or, if none, foreign jurisdiction tax identification number)

    • individual trustee – full legal name, residential address, and IRS tax identification number (if none, foreign jurisdiction tax identification number or non-expired passport number)

    • entity trustee – full legal name, trade name or “doing business as” name, if any, street address of principal place of business, and IRS tax identification number (if none, foreign jurisdiction tax identification number or, if none, foreign jurisdiction entity registration number)

  • individual executing on behalf of transferee entity or trustee and transferor trustee – full legal name, date of birth, residential street address, IRS tax identification number (if none, foreign jurisdiction tax identification number or non-expired passport number), capacity of authorization, and, if the individual is acting in such capacity as employee, agent, or partner, the name of the individual’s employer, principal, or partnership

  • Residential Real Property – street address, legal description (such as section, lot, and block), and date of closing

  • any payments made – amount (including total consideration), method, whether held at a financial institution (name of such institution and account number), and the name of payor

  • any credit extended by a person or entity that is not a financial institution with an obligation to maintain an anti-money laundering program and obligation to report suspicious transactions under the RRE Rule

The RRE Rule impacts a number of common transactions, such as donations of real estate, transfers to revocable trusts, formations of joint ventures where real estate is involved, subdivision planning by real estate developers, cash sales of real estate where banks are not involved, and many others.  Additionally, the RRE Rule captures many non-taxable transactions as well as taxable transactions which would already be reported to the IRS.  For example, if an individual, entity, or trust loans a family entity or trust money to buy a house, this transaction must now be reported to the government pursuant to the RRE Rule.  

As a result of the RRE Rule, the professionals handling Residential Real Property transactions are now required to report information to FinCEN or otherwise face penalties.  Despite concerns as to the privacy of information of United States citizens, the government did not repeal or limit the scope of the RRE Rule as it did with the Corporate Transparency Act. Any entity or trust entering into a transaction closing on or after March 1, 2026, for the transfer of Residential Real Property, and the individuals providing transactional services to them, such as lawyers, title underwriters, title examiners and other persons handling real estate transactions, should keep in mind the RRE Rule. 

For additional information, please visit FinCEN’s Residential Real Estate Reporting page. If you have questions about how the RRE Rule may affect your transactions or compliance obligations, please contact Liskow attorneys Leon Rittenberg III, Caroline Lafourcade, Marilyn Maloney, or Bradford Laperouse.
Blogs

BOEM Takes Next Step Toward Federal Oil and Gas Leasing Offshore California

March 3, 20263 minute read

Featured Image

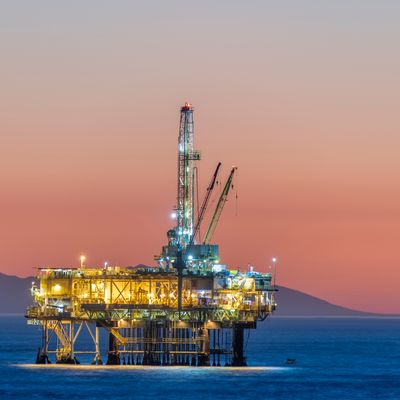
On February 27, 2026, the Bureau of Ocean Energy (“BOEM”) published its Notice of Intent (the “NOI”) to prepare a programmatic environmental impact statement for the Northern, Central and Southern California Planning Areas of the Outer Continental Shelf (the “Programmatic EIS”) in furtherance of proposed oil and gas lease sales in the Pacific Region under the 11th National OCS Oil and Gas Leasing Program (the “11th OCS Program”). The NOI is not an announcement of an oil and gas lease sale, but rather, is the start of information gathering for identifying issues and considering potential alternatives for leasing in the California Planning Areas, none of which have been offered for lease since October 1984, more than 40 years ago. The NOI opens up a 30-day period for public comment on the potential issues, alternatives, and mitigation factors that should be considered under the Programmatic EIS. 

BOEM prepares programmatic environmental impact statements (“PEIS”) on a planning area basis in order to assess potential environmental impacts, and mitigation measures, which may result from the exploration, drilling, operating, and decommissioning of oil and gas leases on the outer continental shelf in the planning area under review. A PEIS is prepared pursuant to the National Environmental Policy Act and seeks to determine whether the environmental impacts from leasing on the blocks to be potentially offered are adequately mitigated. As a result of the findings in a PEIS, certain areas and/or blocks may be excluded by BOEM from oil and gas lease sales. 

As of early 2026, there were 30 active oil and gas leases in the Pacific Region, all in the Southern California Planning Area, representing approximately 152,578 acres out of 205 million acres of the Pacific Region. Only 8 entities hold record title interests in oil and gas leases located in the Southern California Planning Area, with 5 entities serving as operators covering 23 platforms. BOEM estimates that there are 10.20 billion barrels of oil (“Bbo”) and 16.07 trillion cubic feet of natural gas (“Tcf”) of undiscovered technically recoverable reserves in the Pacific Region (with 9.81 Bbo and 13.82 Tcf attributable to the California Planning Areas). 

Six oil and gas lease sales are planned for the Pacific Region under the 11th OCS Program (limited to the Northern, Central, and Southern California Planning Areas) beginning next year.  Two lease sales, covering the Central and Southern California Planning Areas, are planned under the 11th OCS Program to occur in 2027, with three additional sales to be held in 2029, covering the Central, Northern, and Southern California Planning areas, and one final lease sale to be held in 2030, covering the Southern California Planning Area. 

Prospective leaseholders should be aware that BOEM and the Bureau of Safety and Environmental Enforcement (“BSEE”) (acting on behalf of the Secretary of the Department of Interior) coordinate and consult with affected state and local governments in the administration of leasing and regulation of operations under the Outer Continental Shelf Lands Act. Further, under the Coastal Zone Management Act, each federal agency activity affecting the coastal zone is to be carried out in a manner which is consistent with policies of affected state management programs. In addition, state and local governments have jurisdiction over pipeline segments and other facilities in state waters and onshore necessary for offshore oil and gas production. 

Attorneys at Liskow have extensive knowledge and experience with OCS leasing in the Pacific Region, and have assisted clients with matters involving acquiring and transferring Pacific OCS lease interests, including related due diligence, and various regulatory, operational, and decommissioning issues and concerns. We are also familiar with the Pacific Region’s federal regulatory environment.    

For more information regarding this topic, please contact Liskow attorneys Jana Grauberger, Kathleen Doody, and Bradford Laperouse. 

"BOEM invites input from all interested parties, including Federal, State, and local governments, and the general public … on the scope of the California Oil and Gas PEIS, significant issues, reasonable alternatives, potential mitigation measures, and the types of oil and gas activities of interest in the proposed lease sale areas."

www.boem.gov/…

Blogs

Tax Court Rejects § 743(b) Basis Adjustment in Excess of $700 Million

February 26, 20263 minute read

Featured Image

In Otay Project LP, Oriole Management LLC v. Commissioner, T.C. Memo 2026-21, the United States Tax Court disallowed a more than $700 million deduction claimed by a partnership as a § 743(b) basis adjustment and reaffirmed the importance of economic substance in complex tax restructuring. The ruling highlights how rote application of the partnership tax rules cannot override fundamental tax principles, especially in transactions involving aggressive basis adjustment strategies.

Background and Deal Structure: The case involves Otay Project LP (OPLP), a California limited partnership formed to develop Otay Ranch, a 22,000-acre master-planned community in Southern California. Over several years, the partnership sold land tracts pursuant to contracts accompanied by promissory notes, deferring income under the completed contract method (CCM) of accounting, which recognized income only as construction obligations were satisfied. After extended development and internal disputes, the partners executed a series of complex restructuring transactions designed to divide interests and facilitate estate planning. As a result of these transactions and subsequent transfers of upper-tier partnership interests to family trusts, the partnership underwent a technical termination under IRC § 708(b)(1)(B) in 2007. Because OPLP had made a § 754 election, a significant § 743(b) basis adjustment was recorded that purportedly increased inside basis by over $867 million for the benefit of one partner’s successor.

When OPLP later liquidated in 2012 without having completed its construction obligations, the deferred CCM income of more than $716 million became currently taxable. The partnership used the § 743(b) basis adjustment to offset this income and reported a roughly $743 million deduction on its 2012 return. The IRS, in a Notice of Final Partnership Administrative Adjustment (FPAA), disallowed approximately $714 million of the claimed deduction, prompting the Tax Court proceeding.

Tax Court’s Ruling on Basis Adjustment: The Tax Court held that the § 743(b) basis adjustment was fundamentally flawed because the partnership failed to account for the negative capital account and corresponding liabilities that would realistically affect a hypothetical liquidation. The court explained that Treas. Reg. § 1.743-1(d) requires the transferee partner’s share of adjusted basis to be determined based on all relevant rights and obligations, including liabilities reflected in capital accounts. OPLLC’s massive negative capital position, which resulted from prior tax-deferred distributions, directly contradicted the taxpayers’ claimed positive basis adjustment, rendering it incorrect under the statute and regulations.

Economic Substance: The court also sustained the IRS’s alternative position that the restructuring transactions lacked economic substance and should be disregarded under the longstanding substance-over-form doctrine and, by extension, the codified economic substance rules. Although the partners argued that the transactions served valid business and estate planning purposes, the court agreed with the Commissioner that the dominant purpose of the reorganization was tax avoidance. The restructuring produced circular flows of assets with no meaningful change in economic positions other than the tax benefits, which the court found insufficient to satisfy the required nontax business purpose.

Penalties Analysis: Despite disallowing the basis adjustment, the Tax Court declined to impose accuracy-related penalties under IRC §§ 6662(b)(1) and (b)(3). The court found that the partnership and its principals had reasonably relied on extensive advice from highly reputable tax professionals, including leading tax law firms, in a highly complex area of tax law. That finding demonstrated ordinary and reasonable care and negated the Commissioner’s argument that the taxpayers lacked reasonable cause or exhibited negligence.

The decision in Otay Project LP reinforces that mechanical compliance with a regulation does not insulate aggressive tax positions from audit adjustments, particularly under the economic substance doctrine. For more information, contact Liskow attorneys Leon Rittenberg III, Caroline Lafourcade, and Kevin Naccari, and visit Liskow’s Tax Practice page. 

Blogs

From Presumption to Proof: Understanding Louisiana Code of Evidence Article 306.1

February 25, 20263 minute read

Featured Image

For more than thirty years, the Housley presumption shaped personal injury litigation in Louisiana. Since Housley v. Cerise (1991), plaintiffs who were “in good health” before an accident and developed symptoms shortly after could rely on a presumption that the accident caused the injury. That evidentiary shortcut is now gone.

As of May 28, 2025, the Legislature has replaced the presumption with a new codified rule of evidence.

The New Reality: Louisiana Code of Evidence Article 306.1

Louisiana Code of Evidence Article 306.1 now governs causation presumptions in personal injury cases. It provides:

“Notwithstanding any other provision of law, in a claim for personal injury damages that is not raised pursuant to the Louisiana Workers’ Compensation Law, the lack of a prior history of an illness, injury, or condition shall not create a presumption that an illness, injury, or condition was caused by the act that is the subject of the claim.”

This language expressly abolishes the Housley presumption. A plaintiff’s lack of prior complaints and the timing of symptoms no longer create any presumption of causation.

Three Strategic Takeaways for 2026

1. The Burden Is Squarely Back on the Plaintiff

With Article 306.1 now in effect, plaintiffs must affirmatively prove medical causation without the benefit of any presumption. Temporal proximity alone is no longer enough to carry the burden or defeat summary judgment. Medical testimony and documented clinical linkage will be required from the outset.

2. A Transitional, Not Truly Bifurcated, Landscape

Article 306.1 became effective on May 28, 2025, and—because it is a substantive change—it applies prospectively. Practically, this means:

  • Claims arising before May 28, 2025 may still invoke Housley.
  • Claims arising after May 28, 2025 are governed by Article 306.1.

In cases involving multiple accidents, progressive symptoms, or a course of treatment that crosses the effective date, courts will have to determine whether the injury is divisible or whether Article 306.1 governs the entire claim. Until those decisions develop, the presumption is effectively confined to older, pre‑May 28, 2025 injuries.

Importantly, Article 306.1 does not apply to workers’ compensation claims, which retain their traditional causation standards.

3. The “Double Whammy” of Louisiana’s Medical Expense Reform

The end of Housley coincides with another major reform: a new statutory framework governing recoverable medical expenses, effective January 1, 2026. Under this reform, plaintiffs generally may recover only the amounts actually paid for medical treatment, subject to limited statutory exceptions.

Together, these changes reshape exposure:

  • Article 306.1 eliminates the presumption that the plaintiff’s injury/illness was caused by the alleged tort, thereby requiring the plaintiff to affirmatively prove medical causation. The medical expense reforms reduce recoverable medical damages even when causation is established.

For defendants and insurers, this combination materially lowers risk. For plaintiffs, it raises both the evidentiary and economic hurdles.

Impact: What This Means for Litigation Strategy

These changes should influence how personal injury cases are defended, valued, and resolved:

  • Stronger Summary Judgment Opportunities: Without a causation presumption, plaintiffs must produce competent admissible medical evidence early, making causation-based summary judgment motions more viable.
  • Earlier Expert Involvement: Defense teams benefit from earlier medical reviews, IMEs, and expert input to challenge causation and shape discovery.
  • Settlement Leverage: Higher evidentiary burdens and lower recoverable medicals can push valuations downward and strengthen defense positions in negotiation.
  • Lower Case Valuations Overall: With causation harder to prove, and medical damages tied to amounts actually paid, exposure drops — especially in soft-tissue and delayed-onset injury cases.

The Practical Effects

The Housley presumption once filled gaps in medical proof and often shifted the burden toward defendants. With Article 306.1 now codified and new medical expense rules taking effect, Louisiana has entered a new era of personal injury litigation—one that demands stronger medical evidence, earlier expert involvement, and more proactive causation strategy.

The era of the “presumed injury” is over. The era of documented, defensible causation has emerged.

Notwithstanding any other provision of law…the lack of a prior history of an illness, injury, or condition shall not create a presumption that an illness, injury, or condition was caused by the act that is the subject of the claim.

www.legis.la.gov/…

Blogs

IRS Issues Interim Guidance on Special Depreciation Allowance Under the OBBBA

February 20, 20262 minute read

Featured Image

On February 20, 2026, the Department of the Treasury and the Internal Revenue Service (IRS) released Notice 2026-16, providing interim guidance on the special depreciation allowance for qualified production property enacted as part of the One, Big, Beautiful Bill Act (OBBBA). This statutory provision, added to Internal Revenue Code § 168(n), authorizes a temporary 100 percent “bonus” depreciation deduction for qualified production property placed in service within specified dates. Notice 2026-16 provides taxpayers with interim administrative rules ahead of formal proposed and final regulations addressing this new regime.

The Notice clarifies definitional and operational elements of the special depreciation allowance that are essential for compliance. It explains what constitutes qualified production property (generally nonresidential real property used as an integral part of a qualified production activity, such as manufacturing or refining, that results in a substantial transformation of property). The Notice also identifies the timeframes within which the property must be placed in service to qualify for the allowance, including possible extensions of time due to an “act of God.” The interim guidance further addresses the mechanics of electing into the special depreciation regime and the necessary attachment of an election statement to timely filed income tax returns.

Notice 2026-16 also provides taxpayers with practical rules on property eligibility, including de minimis tests and safe harbors for determining whether a property meets the statutory criteria. This guidance is intended to be binding on taxpayers who follow its entirety, creating a workable framework for claiming the special depreciation allowance until the IRS issues proposed regulations that will formally implement the statutory provisions. Taxpayers and practitioners are encouraged to review the interim rules carefully and to provide comments by April 20, 2026 to assist the IRS and Treasury in refining the forthcoming regulations.

Notice 2026-16 represents an important step in the IRS’s rollout of OBBBA’s broad depreciation reforms by giving taxpayers clarity and operational certainty on the application of the new § 168(n) bonus depreciation rules while formal regulatory guidance is under development. For more information, contact Liskow attorneys Leon Rittenberg III, Caroline Lafourcade, and Kevin Naccari, and visit Liskow’s Tax Practice page. 

Blogs

AI Communications Are Not Privileged: What United States v. Heppner Means for the Defense Bar and Corporate Clients

February 19, 20264 minute read

Featured Image

In a significant decision rendered this week, Judge Jed S. Rakoff of the Southern District of New York held that written exchanges between a criminal defendant and a generative AI platform were protected by neither attorney-client privilege nor the work product doctrine. United States v. Heppner, 25 Cr. 503 (JSR) (S.D.N.Y. Feb. 17, 2026). 

The ruling is one of the first federal decisions squarely addressing privilege in the context of generative AI — and it carries immediate implications for defense counsel and corporate and industrial clients navigating litigation risk in an AI-saturated world. The source of the Heppner decision (the often-influential Southern District of New York) further underscores its significance.

The Core Ruling: AI Is a “Third Party” 

Judge Rakoff described the question as one “of first impression nationwide”: whether communications with a publicly available AI platform in connection with a pending criminal investigation are protected by attorney-client privilege or work product doctrine (Order at 2).

The court’s answer was direct: “the answer is no” (Order at 2). 

The defendant had used Anthropic’s Claude to generate written analyses outlining potential defense strategies after receiving a grand jury subpoena and after discussions with the government made clear he was a target (Order at 3). Claude is a “Large Language Model,” similar to ChatGPT and Google Gemini.

The defendant later shared those AI-generated documents with counsel. The government sought a ruling that the materials were not privileged.

The court began by reciting the traditional elements of attorney-client privilege: communications between client and attorney, intended to be confidential, and made for the purpose of obtaining legal advice (Order at 4). The AI documents failed on multiple grounds.

1. AI platforms are not attorneys.

The court emphasized that the AI documents were “not communications between Heppner and his counsel” and that “Claude is not an attorney” (Order at 5). Because discussions of legal issues with non-attorneys are not privileged, that fact alone was dispositive (Order at 5).

Privilege depends on a “trusting human relationship” with a licensed professional owing fiduciary duties – and no such relationship exists with an AI platform (Order at 6).

2. No reasonable expectation of confidentiality.

The court also found that the defendant lacked any reasonable expectation of confidentiality in his interactions with Claude. The court relied on Claude’s privacy policy, noting it permits collection of user inputs and outputs, use of data to train models, and disclosure to third parties, including governmental authorities (Order at 6). 

Critically, the court held that forwarding the AI outputs to counsel does not retroactively cloak them in privilege. Because the communications were not privileged “at the time they took place,” they did not become privileged merely because they were later shared with an attorney (Order at 8). 

3. Any privilege was waived.

The defendant’s final argument was that much of the information he inputted into Claude constituted information he had received from his counsel, thus making it privileged and confidential. The court disagreed, holding that even if privilege had attached to the information at one point, the defendant waived the privilege by inputting the information into Claude, “just as if he had shared it with any other third party.” (Order at 8, footnote 3). The court rejected the defendant’s proposed analogy that inputting privileged information into an AI model was the equivalent of saving or transmitting it via other cloud-based platforms (e.g., an e-mail server or a file-sharing service) – while other digital platforms may offer an expectation of privacy, Claude does not. (Order at 5-8).

4. Work product doctrine does not attach to interactions with AI platforms.

The court then turned to work product doctrine, which protects materials prepared “by or at the behest of counsel in anticipation of litigation” (Order at 9).

Even assuming the AI documents were created in anticipation of litigation, they still failed the doctrine’s core requirement – they were not prepared “by or at the behest of counsel” (Order at 9). Rather, they were prepared by the defendant “on his own volition,” and they did not reflect counsel’s strategy at the time they were created (Order at 10). The court’s ruling adheres to the general rule that the work product doctrine exists to protect lawyers’ mental processes.

The Conclusion: AI Is Subject to Traditional Privilege Rules

Judge Rakoff closed with a measured but clear statement: AI may represent a “new frontier,” but that “does not mean that its use is not subject to longstanding legal principles” governing attorney-client privilege and work product doctrine (Order at 12). Because the defendant’s use of Claude did not satisfy those principles, the materials were discoverable (Order at 12).  

Lingering Questions

The Heppner court did not address several followup questions, which will inevitably be litigated in future cases, such as:

  • Would the result have been different if the defendant had used a “closed” AI platform (i.e., one guaranteeing confidentiality) versus an “open” platform such as Claude?
  • What is the scope of the defendant’s waiver of privilege – i.e., does inputting privileged information into a third-party AI platform effect a broader subject-matter waiver, potentially exposing related communications between client and counsel on the same topic?
  • Even if discoverable, are such conversations admissible under relevance principles, particularly where the exchanges reflect exploratory brainstorming rather than concrete information?
  • Are a litigant’s conversations with an AI platform a “statement of a party” and potentially a “statement against interest” under the hearsay rules? What about the responses of the AI platform?
  • Would the result be different if a litigant interacts with an AI platform provided by counsel or at the direction of counsel? 

What This Means for Corporate Litigants and Their Counsel 

Companies increasingly use AI to analyze crisis response, draft public statements, or evaluate regulatory exposure after a catastrophe. Heppner makes clear:

  • AI-generated internal strategy documents may be discoverable.
  • Consumer-grade AI platforms create confidentiality risk.
  • If AI is used in litigation contexts, counsel should consider directing and controlling its use, and alleged contractual protections should be evaluated carefully.

For corporate actors navigating high-stakes public events — environmental incidents, product recalls, regulatory investigations — Heppner is a wake-up call: AI is not a privileged advisor.

For defense lawyers, Heppner makes clear that the universe of discoverable information is continuing to expand. Lawyers should consider advising their clients on the risk of inadvertently creating discoverable information (or waiving privilege over otherwise privileged information) by interacting with AI platforms. 

Lawyers should also consider Heppner when evaluating the cost and risk involved in defending a piece of litigation. They should consider engaging in early conversations with their clients about what AI-related paper trails exist, to avoid costly surprises once litigation reaches advanced stages.  

For further questions regarding the Heppner decision and related AI and privilege issues, contact Liskow attorney Michael Mims and visit our Environmental and Toxic Tort practice pages.


[E]ven if certain information that Heppner input into Claude was privileged, he waived the privilege by sharing that information with Claude and Anthropic, just as if he had shared it with any other third party.

storage.courtlistener.com/…

Blogs

LDR Streamlines PTE Election Documentation Requirements

February 18, 20262 minute read

Featured Image

The Louisiana Department of Revenue (“LDR”) has issued Revenue Information Bulletin 26-007, announcing a change to the documentation required for shareholders, partners, and members of entities that elect to pay Louisiana’s Pass-Through Entity (“PTE”) tax beginning with the 2025 taxable year. Owners of electing PTEs will no longer be required to submit a pro forma federal income tax return or nonresident worksheet with their initial Louisiana filing.

Existing regulation LAC 61:I.1001(C)(4)(d) requires each owner to submit Form R-6981, Statement of Owner’s Share of Entity Level Tax Items, together with a pro forma federal return (Form 1040 or 1041 for residents). Each nonresident owner must submit a worksheet from Louisiana Form IT-540B. Revenue Information Bulletin 26-007 provides that, starting in 2025, owners must still submit Form R-6981, but the pro forma federal return or nonresident worksheet will be required only upon request by LDR. The Department intends to amend LAC 61:I.1001 to reflect this revised requirement.

The Bulletin also reiterates that the PTE election does not change the total amount of income subject to Louisiana tax. In no event may Louisiana taxable income be greater or less than it would have been absent the election. Where the deduction reported on Form R-1968 does not accurately reflect Louisiana taxable income, taxpayers are encouraged to submit a pro forma federal return or nonresident worksheet to support the correct computation, even if not initially required.

This update reduces administrative burdens while preserving LDR’s ability to verify reported income through document requests. Taxpayers making the PTE election should adjust their filing procedures for 2025 and beyond and continue to maintain supporting documentation in anticipation of potential review by the Department. For more information, contact Liskow attorneys Bob Angelico, Leon Rittenberg III, Caroline Lafourcade, and Kevin Naccari, and visit Liskow’s Tax Practice page. 

Blogs

Second Circuit Affirms Tax Liability resulting from S Corporation ownership

February 13, 20263 minute read

Featured Image

On February 9, 2026, the United States Court of Appeals for the Second Circuit  upheld an individual income-tax deficiency and associated penalties against taxpayer Karen Veeraswamy for the 2014 tax year. The court’s decision reinforces the principle of consistency in taxpayer representations, the presumption of correctness of IRS deficiency notices, and the limited function of Tax Court Rule 155 computations. Veeraswamy v. Commissioner highlights the risks taxpayers face when their representations in one forum are used against them in another forum.

The underlying dispute centered on whether Ms. Veeraswamy was a 50 percent shareholder of Ashand Enterprises who realized capital gains and rental income in 2014. The Commissioner determined that Veeraswamy, was a half-owner of Ashand, and was liable for tax on her pro rata share of the corporation’s income. The taxpayer claimed she was not a stockholder of the company in 2014.

The Second Circuit’s analysis focused on the role of judicial estoppel and consistency of representations across proceedings. Although Veeraswamy argued that Ashand’s bankruptcy proceedings established that her then-husband was the sole owner, the appellate court agreed with the Tax Court that the bankruptcy confirmation order did not resolve the ownership issue on the merits and thus did not preclude the IRS’s contrary position. The court applied federal preclusion law, concluding that neither claim preclusion nor issue preclusion barred the Commissioner from litigating ownership because the bankruptcy court did not enter a final decision adjudicating Veeraswamy’s ownership interest and the issue was not “actually litigated and decided” in that forum.

Moreover, the Second Circuit emphasized that the Commissioner’s tax deficiency assessment had a rational basis, which triggered the statutory presumption of correctness applicable to IRS notices of deficiency. Veeraswamy’s own statements in the bankruptcy proceedings that she was a 50 percent shareholder of Ashand provided a rational connection between the taxpayer and the corporation’s income, supporting the IRS’s determination. The court also noted that Veeraswamy failed to produce contemporaneous documentation substantiating her claimed lack of ownership or contributions to Ashand at trial, and therefore did not rebut the presumption of correctness.

The Second Circuit also upheld the Tax Court’s handling of the Rule 155 computation process. Veeraswamy attempted to use Tax Court Rule 155 to introduce additional deductions for taxes, utilities, and building expenses that she argued should reduce her tax liability, but the court found that these arguments sought to relitigate issues already decided on the merits. Rule 155 is intended solely for mechanical computation of tax liability based on established findings, not as a vehicle to raise new substantive issues or reargue matters already resolved. The appellate court therefore found no abuse of discretion in the Tax Court’s rejection of these post-opinion computations.

Finally, the Second Circuit affirmed the imposition of penalties under Internal Revenue Code § 6651(a) for failure to file and pay. Veeraswamy argued that she had reasonable cause based on accounting consultations, but the court agreed with the Tax Court that mere consultation with an accountant, without specific advice to the effect that she had no obligation to file or pay, did not establish reasonable cause. The court also rejected her arguments concerning estimated tax penalties, finding that speculative concerns about potential criminal liability did not qualify as casualty, disaster, or unusual circumstances warranting penalty relief.

The Veeraswamy decision demonstrates that inconsistent representations across legal proceedings can have significant tax consequences and that taxpayers must be attentive to how assertions made in one forum, including bankruptcy court, may affect tax liability in another forum. It also reinforces the principle that the Tax Court’s Rule 155 process is procedural and not a means to reopen or expand factual and legal determinations already made on the merits. If you have questions about this update, please contact Liskow attorneys Leon Rittenberg III, John Rouchell, Caroline Lafourcade, and Kevin Naccari and visit our Tax practice page. 

Blogs

Federal Court Upholds IRS Promoter Penalties Against Art Donation Program Operator Under IRC Section 6700

February 6, 20263 minute read

Featured Image

A federal district court in Texas recently granted summary judgment in favor of the United States in a case involving penalties assessed against the operator of an art donation program that marketed charitable contribution tax deductions based on inflated appraisals and questionable ownership arrangements. The decision reinforces the Internal Revenue Service’s authority to impose substantial promoter penalties under Internal Revenue Code Section 6700 and provides important guidance on what constitutes false or fraudulent statements regarding tax benefits.

Abbey Art Consultants, Inc., a company founded and controlled by David Ehrlich, engaged in the business of acquiring artwork, storing it, and facilitating its donation to charitable organizations so that customers could claim charitable contribution deductions equal to the artworks’ appraised fair market value. Customers typically paid a small deposit, often only five to ten percent of the quoted purchase price, and were told that ownership of the artwork began when pieces were “set aside” for them in storage. Abbey Art then held the artwork for approximately one year before arranging for donation and providing customers with appraisals and prefilled tax documentation claiming deductions significantly higher than the amounts paid for the art.

In 2021, the IRS assessed penalties against Ehrlich under Section 6700 for promoting an abusive tax shelter through false statements concerning the availability of tax benefits. After Ehrlich paid a portion of the penalty and filed a refund suit, the government counterclaimed for additional penalties exceeding $1 million. Following Ehrlich’s death, his estate was substituted as the plaintiff.

The court first addressed the applicable standard of proof for Section 6700 violations. Although many courts apply a preponderance of the evidence standard, the court adopted a clear and convincing evidence standard based on Fifth Circuit precedent and analogous fraud provisions in the Internal Revenue Code. Applying that heightened standard, the court concluded that the government had met its burden on all required elements.

To establish liability under Section 6700(a)(2)(A), the government was required to show that Ehrlich made or caused others to make false or fraudulent statements about material matters relating to tax benefits and that he knew or had reason to know the statements were false. The court found clear and convincing evidence that Ehrlich made material misrepresentations in two primary areas. First, he represented to clients that they acquired ownership of artwork when it was segregated in storage or when a small deposit was paid. Second, he advised clients that they could claim charitable deductions based on appraised values and rely on those appraisals for tax purposes.

The court concluded that customers did not obtain ownership of the artwork when it was merely set aside because clients had no binding obligation to pay the remaining balance and Abbey Art could not enforce payment. Accordingly, the arrangements amounted to options to purchase rather than completed sales. Without a transfer of ownership, the on-year holding period never commenced.

The court also rejected the estate’s argument that client testimony regarding their subjective belief that they owned the art was sufficient to create a factual dispute. The absence of enforceable contracts, the ability to refund or revise deposits, and the lack of client possession or identification of specific artwork supported the conclusion that Ehrlich’s ownership representations were false as a matter of law.

Further, the court found that Ehrlich knew or should have known that his statements were false. He did not rely on advice from tax professionals, exercised full control over the company’s operations, and was a sophisticated businessperson familiar with tax matters. Importantly, Ehrlich was aware of prior court decisions rejecting similar Abbey Art arrangements, which directly undermined his representations regarding ownership and holding periods. The court also held that statements made by Abbey Art’s employee could be attributed to Ehrlich because he directed and controlled the business and caused the statements to be made within the meaning of Section 6700.

Finally, the court upheld the IRS’s penalty calculation methodology. Section 6700 authorizes a penalty equal to 50 percent of the gross income derived from the prohibited activity. The court agreed with the government that the penalty should be based on Abbey Art’s overall gross income from the program rather than requiring proof of false statements for each individual transaction.

This decision highlights the risks faced by promoters of donation-based tax strategies and similar programs that depend on aggressive interpretations of ownership, valuation, or holding period rules. Courts will closely scrutinize whether customers truly acquire property interests sufficient to support charitable contribution deductions and whether promoters’ representations align with established tax law. The ruling also highlights the broad reach of Section 6700, including the IRS’s ability to impose penalties equal to half of the gross income generated by an abusive scheme and to attribute employee statements to the individual controlling the operation. 

As enforcement efforts continue to focus on abusive charitable deduction arrangements and tax shelter promotions, this case serves as a reminder that misstatements about tax benefits can lead to significant penalty exposure and litigation risk. If you have questions about this update, please contact Liskow attorneys Leon Rittenberg III, John Rouchell, Caroline Lafourcade, and Kevin Naccari and visit our Tax practice page. 

Blogs

Proposed Regulations for Section 45Z Clean Fuel Production Credit, Provide Greater Certainty for Biofuel Producers

February 4, 20262 minute read

Featured Image

The Internal Revenue Service recently released proposed regulations implementing the Section 45Z Clean Fuel Production Credit after statutory changes enacted in last year’s tax legislation expanded and extended the credit through 2029. Although the rules are not yet final, the proposed regulations provide long-awaited clarity after years of uncertainty and are expected to encourage additional investment in low-carbon fuel production.

Section 45Z replaced a collection of prior fuel tax incentives and adopts a technology-neutral approach that rewards transportation fuels produced using low-emission methods. The value of the credit depends on the lifecycle greenhouse gas emissions of the fuel, making emissions modeling central to determining eligibility and benefit amounts. Farmers, fuel producers, fuel sellers, and airlines may all benefit from the credit, which applies to qualifying fuels produced beginning in 2025.

A key change in the proposed regulations revises guidance issued earlier this year that would have significantly limited eligibility by restricting “qualified sales” to fuel users only. That interpretation conflicted with standard industry distribution practices, which frequently involve wholesalers, dealers, and other intermediaries. The revised proposal broadens the definition of qualified sales, allowing sales through customary commercial channels to qualify for the credit. This change removes a major obstacle that had raised concerns among producers and potential credit purchasers and threatened to curtail participation in the program.

The proposed regulations also introduce compliance safe harbors related to substantiating emissions rates and documenting qualified sales. These provisions are intended to reduce administrative burdens and audit risk for taxpayers while providing a more workable framework for calculating and claiming the credit. Collectively, these revisions signal a more practical and commercially aligned regulatory approach.

Despite this progress, important uncertainties remain. Fuel producers continue to await updated guidance from the Department of Energy regarding the emissions modeling framework that taxpayers must use to calculate lifecycle greenhouse gas rates. Because emissions intensity directly determines the amount of the credit, this forthcoming model will play a central role in shaping both eligibility and economic outcomes for producers.

The Section 45Z credit has drawn bipartisan support but also criticism regarding its fiscal impact and effectiveness in reducing consumer fuel prices. The Joint Committee on Taxation estimates that the extension and expansion of the credit will reduce federal revenues by approximately $25.7 billion over the 2025–2034 period. Critics argue that the credit disproportionately benefits fuels derived from corn and soybeans that already receive support under other public policies.

Nevertheless, the IRS’s proposed regulations represent a meaningful step toward regulatory certainty and program viability. By aligning the rules more closely with industry practices and providing substantiation safe harbors, the proposal is expected to increase market confidence and stimulate additional investment in clean fuel production. 

Fuel producers, distributors, and investors should begin evaluating how the proposed rules may affect their operations and consider submitting comments during the rulemaking process to address remaining technical and practical concerns. If you have questions about this update, please contact Liskow attorneys Leon Rittenberg III, John Rouchell, Caroline Lafourcade, and Kevin Naccari and visit our Tax practice page. 

Blogs

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 8
  • Page 9
  • Page 10
  • Page 11
  • Page 12
  • Interim pages omitted …
  • Page 188
  • Go to Next Page »

Primary Sidebar

Recent Posts

  • IRS Permits Entity Classification Change Following Significant Ownership Change
  • A Spirited Debate: Supreme Court to Review Federal Ban on Home Distilling
  • “Credit or Debit?”: IRS Issued Final Regulations Simplifying Tax Payments by Credit or Debit Card
  • Considering an ESOP? New Law Reduces Valuation Risk
  • EPA Finalizes Rule Clarifying “Applicable Requirements” Under Title V Program

Categories

  • Blogs
  • Events
  • Insights
  • News
Liskow & Lewis, APLC
Arrow Icon

future-focused

  • Baton Rouge
  • Houston
  • Lafayette
  • New Orleans
  • New York City
  • New Bedford
  • © 2026 Liskow & Lewis, APLC
  • Sitemap
  • Disclaimer
  • Employee Login
Site by
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
Cookie SettingsAccept All
Manage consent

Privacy Overview

This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary
Always Enabled
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
CookieDurationDescription
cookielawinfo-checkbox-analytics11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional11 monthsThe cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy11 monthsThe cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytics
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Others
Other uncategorized cookies are those that are being analyzed and have not been classified into a category as yet.
SAVE & ACCEPT
  • Team
  • Practices
  • Insights
  • Blogs
  • Offices
  • Pro Bono
  • About Us
  • Careers
  • DEI
  • The Energy Law Blog
  • Gulf Coast Business Law Blog
  • The Maritime Law Blog