• Skip to content
  • Skip to primary sidebar

liskow_lewis_white_new

future-focused

  • Team
  • Practices
  • Insights
  • Blogs
    • Energy Law Blog
    • Gulf Coast Business Law Blog
    • Maritime Law Blog
    • Louisiana Industrial Insights Hub

Blogs

SCOTUS Presented with Best Opportunity to Weigh In on Climate Change Litigation

December 3, 20252 minute read

Featured Image


The United States Supreme Court is currently presented with what many believe is the best opportunity for the Court to provide sorely needed guidance in the vastly growing climate change docket—where energy companies are facing liability for injuries allegedly sustained due to greenhouse gas emissions. In Suncor Energy (U.S.A.) Inc., et al. v. County Commissioners of Boulder County, energy companies are asking the Supreme Court to decide whether federal law precludes state law nuisance claims targeting interstate and global emissions.  The state trial court denied the defendants’ motion to dismiss the suit brought by the City and county of Boulder, finding that federal law did not preempt the state law claims. The Colorado Supreme Court granted the energy companies’ request to review the decision and affirmed, with two justices dissenting.

In urging the Supreme Court to take the case, the energy companies note that the decision of the Colorado Supreme Court, which paves the way for Boulder to proceed to trial on claims attacking global emissions, conflicts with a 2021 decision from the United States Second Circuit in City of New York v. Chevron Corp. In City of New York, the Second Circuit held that federal law preempts state law claims when those claims reach beyond the state’s borders and attempt to target the defendants’ nationwide and global operations. Notably, the United States filed an amicus brief in support of the energy companies in Suncor, asking the Supreme Court to take up the case which presents “a frequently occurring issue of exceptional importance.” United States Amicus at 3.

For its part, Boulder argues, among other things, that this is not the “right case” or the “right time” for the Supreme Court to tackle the thorny climate change litigation.  Boulder Response at 17. According to Boulder, the decision of the Colorado Supreme Court is only interlocutory and thus if the Court prematurely takes up the case at this time, it would be wading “into a thicket of preliminary questions that promise nothing but rabbit holes and dead ends.” Boulder Opposition at 1. Last week, the energy companies replied strongly that “if not now, when?” Suncor Reply at 10. The companies made a compelling pitch that “[w]hile the defendants in these cases will theoretically be able to seek review after liability is imposed, that is cold comfort given the growing number of cases and the sheer magnitude of the potential liability.” Suncor Reply at 10. To emphasize this point, the energy companies pointed to a statement describing the nationwide climate change litigation as a “carbon tax” aimed at crippling the entire industry. Suncor Reply at 2. Ultimately, the companies contend that the issue presented is paramount in our constitutional system: can state law tort suits effectively regulate interstate, and international, energy policies?  This closely watched case is now poised for SCOTUS to decide whether it will grant the cert petition.

Stay tuned for more climate change litigation updates from Liskow attorneys Kelly Becker, Jamie Rhymes, and James Lapeze.
 

Blogs

Greenwashing Hits Home: New Washington Lawsuit Alleges Climate Deception by Fossil Fuel Companies is Linked to Rising Home Insurance Premiums

December 2, 20252 minute read

A newly filed class action in the Western District of Washington advances a novel theory of greenwashing liability by suggesting that rising homeowners-insurance premiums are tied to alleged decades of climate deception by major fossil-fuel companies.  See Kennedy & Hazard v. Exxon Mobil Corp. et al., Case No. 2:25-cv-02378. According to the complaint, extreme weather events in the United States doubled in the 50 years between 1960 and 2010. In the first 3 quarters of 2024, these catastrophic events produced nearly $145 billion in total economic losses, with almost $80 billion covered by insurance, a trend the plaintiffs say has fueled a nationwide surge in premiums.  

The plaintiffs, two Washington homeowners, contend their own premiums more than doubled in recent years and claim these increases allegedly stem from the deception of fossil fuel companies in their promotion of their products. Central to the lawsuit is the allegation that the defendants maintained internal knowledge for decades that continued use of fossil fuel would significantly warm the planet, increase catastrophic weather events, and harm the public. Despite that knowledge, plaintiffs claim the defendants engaged in coordinated efforts “deliberately misleading consumers” about the risks their products posed, thereby prolonging fossil-fuel dependence and “precipitating a homeowners insurance crisis.”

According to plaintiffs, insurers have responded to these losses “brought about by Defendants’ misconduct” by increasing premiums in response to the growing frequency and severity of climate-linked disasters. The complaint draws several comparisons to the “big-tobacco playbook” while primarily fitting its allegations under the Racketeering Influenced and Corrupt Organizations Act.

The two plaintiffs seek to be representatives for two classes of plaintiffs: a national class encompassing all homeowners in the United States who have home insurance and a subclass of Washington homeowners with home insurance. Both classes are defined to include only homeowners since 2017 but both classes purport to include future homeowners who will hold a home insurance policy.

The plaintiffs’ approach represents a new frontier in climate litigation: an attempt to treat insurance-market impacts as recoverable economic injuries traceable to alleged climate deception. This lawsuit introduces a potentially far-reaching dimension to climate-related liability that should be watched closely.

For more information on this case, contact Liskow attorneys Kelly Becker, Jamie Rhymes, James Lapeze, and Andrew Hughes.

Blogs

Greenwashing Hits Home: New Washington Lawsuit Alleges Climate Deception by Fossil Fuel Companies is Linked to Rising Home Insurance Premiums

December 2, 20252 minute read

Featured Image


A newly filed class action in the Western District of Washington advances a novel theory of greenwashing liability by suggesting that rising homeowners-insurance premiums are tied to alleged decades of climate deception by major fossil-fuel companies.  See Kennedy & Hazard v. Exxon Mobil Corp. et al., Case No. 2:25-cv-02378. According to the complaint, extreme weather events in the United States doubled in the 50 years between 1960 and 2010. In the first 3 quarters of 2024, these catastrophic events produced nearly $145 billion in total economic losses, with almost $80 billion covered by insurance, a trend the plaintiffs say has fueled a nationwide surge in premiums.  

The plaintiffs, two Washington homeowners, contend their own premiums more than doubled in recent years and claim these increases allegedly stem from the deception of fossil fuel companies in their promotion of their products. Central to the lawsuit is the allegation that the defendants maintained internal knowledge for decades that continued use of fossil fuel would significantly warm the planet, increase catastrophic weather events, and harm the public. Despite that knowledge, plaintiffs claim the defendants engaged in coordinated efforts “deliberately misleading consumers” about the risks their products posed, thereby prolonging fossil-fuel dependence and “precipitating a homeowners insurance crisis.”

According to plaintiffs, insurers have responded to these losses “brought about by Defendants’ misconduct” by increasing premiums in response to the growing frequency and severity of climate-linked disasters. The complaint draws several comparisons to the “big-tobacco playbook” while primarily fitting its allegations under the Racketeering Influenced and Corrupt Organizations Act.

The two plaintiffs seek to be representatives for two classes of plaintiffs: a national class encompassing all homeowners in the United States who have home insurance and a subclass of Washington homeowners with home insurance. Both classes are defined to include only homeowners since 2017 but both classes purport to include future homeowners who will hold a home insurance policy.

The plaintiffs’ approach represents a new frontier in climate litigation: an attempt to treat insurance-market impacts as recoverable economic injuries traceable to alleged climate deception. This lawsuit introduces a potentially far-reaching dimension to climate-related liability that should be watched closely.

For more information on this case, contact Liskow attorneys Kelly Becker, Jamie Rhymes, James Lapeze, and Andrew Hughes.

Blogs

DOI Issues Draft Proposed 2026-2031 National Outer Continental Shelf Oil and Gas Leasing Program: Sales Scheduled for Alaska, Gulf of America, and Pacific Regions

December 1, 20256 minute read

On November 24, 2025, the U.S. Department of Interior (DOI) published its Notice of Availability of the 1st Analysis and Proposal of the Draft Proposed Program (DPP) for the 11th National Outer Continental Shelf (OCS) Oil and Gas Leasing Program (11th OCS Program), opening up a statutorily required 60-day public review and comment period on the DPP in order to assist the Secretary of Interior in its determination of which areas to include in the final, approved program.  In furtherance of the ongoing implementation of President Trump’s Executive Order 14154, entitled “Unleashing American Energy,” the DPP (i) is the second of five steps in the Federal government’s process of developing a new five-year plan for holding offshore oil and gas lease sales on the Outer Continental Shelf (OCS), consistent with the Outer Continental Shelf Lands Act, 43 U.S.C. § 1331, et seq., and (ii) once approved, is expected to terminate and replace the 10th National OCS Oil and Gas Leasing Program (10th OCS Program) promulgated under the Biden administration, which is ongoing and currently set to expire on June 30, 2029.  As proposed, the DPP covers acreage in the Alaska, Gulf of America, and Pacific Regions of the OCS and aims to make more than 85% of the estimated technically recoverable OCS oil and gas resources available for sale during the five-year period following approval of the 11th OCS Program.  Pursuant to the DPP, “Inclusion of an area in [the DPP] is not a final indication that it will be included in the approved 11th [OCS] Program, or offered in a lease sale, because additional decision points remain to potentially reduce or completely remove an area or sale.”

Unlike prior National Leasing Programs, the Bureau of Ocean Energy Management (BOEM) plans to prepare an environmental analysis outside of the typical programmatic environmental impact statement under the National Environmental Policy Act (NEPA) for the 11th OCS Program (instead BOEM will prepare NEPA review on a lease basis pursuant to an environmental assessment, environmental impact statement, or determination of NEPA adequacy). Additionally, the 11th OCS Program would be the first implemented program to cover the areas within BOEM’s new jurisdictional limits, as revised by DOI on April 30, 2025, which increased the number of planning areas from 26 to 27, but decreased the total acreage offered from approximately 1.72 billion acres to 1.68 billion acres. As currently proposed, the DPP for the 11th OCS Program comprises 21 of the 27 the planning areas, consisting of 1.27 billion acres, and proposes the following lease sale schedule:

No.Sale YearOCS RegionProgram Area
12026AlaskaBeaufort Sea Program Area
22027PacificSouthern California Program Area
32027PacificCentral California Program Area
42027Gulf of AmericaGOA Program Area A
52027AlaskaCook Inlet Program Area
62028AlaskaChukchi Sea Program Area
72028Gulf of AmericaGOA Program Area A
82028AlaskaCook Inlet Program Area
92029PacificSouthern California Program Area
102029PacificNorthern California Program Area
112029PacificCentral California Program Area
122029Gulf of AmericaGOA Program Area A
132029Gulf of AmericaGOA Program Area B
142029AlaskaCook Inlet Program Area
152030AlaskaGulf of Alaska Program Area
162030AlaskaShumagin Program Area
172030AlaskaKodiak Program Area
182030Gulf of AmericaGOA Program Area B
192030Gulf of AmericaGOA Program Area A
202030AlaskaCook Inlet Program A
212030PacificSouthern California Program Area
222030AlaskaChukchi Sea Program Area
232030AlaskaBeaufort Sea Program Area
242030AlaskaHope Basin Program Area
252030AlaskaNorton Basin Program Area
262030AlaskaNavarin Basin Program Area
272030AlaskaSt. George Basin Program Area
282030AlaskaHigh Arctic Program Area
292031Gulf of AmericaGOA Program Area A
302031AlaskaCook Inlet Basin Program Area
312031AlaskaAleutian Basin Program Area
322031AlaskaAleutian Arc Program Area
332031AlaskaBowers Basin Program Area
342031AlaskaSt. Matthew-Hall Program Area

Notably, the DPP proposes leasing acreage in the Central, Northern, and Southern California Planning Areas, which have not been offered for lease in over forty years. The DPP also reflects the Secretary of Interior’s intent to (i) make available for leasing a newly created South-Central GOA Planning Area, designated on the table above, as GOA Program Area B, which is located in the southwestern portion of the current Eastern GOA Planning Area and, (ii) remove the remaining Eastern GOA Planning Area from further leasing under the 11th OCS Program.

Below is a comparison of the 11th OCS Program, as currently proposed, on the four OCS Regions versus the 10th OCS Program’s impact on these same regions:

Atlantic Region

As of September 1, 2025, there were no active leases in the Atlantic Region. The last sale of acreage located in the Atlantic Region took place on July 26, 1983, and offered 3,582 tracts (approximately 20.15 million acres) in the Southern Atlantic, with 11 tracts (approximately 62.62 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Atlantic Region.

The DPP for the 11th OCS Program, as currently proposed, does not plan to offer for sale any acreage in the Atlantic Region.

Alaska Region

As of September 1, 2025, there were 11 active leases in the Alaska Region (approximately 55.97 thousand acres), 3 of which are actively producing (approximately 10.42 thousand acres). The last sale of acreage located in the Alaska Region took place on December 30, 2022, and offered 193 tracts (approximately 958.20 thousand acres) in the Cook Inlet, with 1 tract (approximately 5.69 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Alaska Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 21 lease sales in the Alaska Region.

Gulf of America Region

As of September 1, 2025, there were 2,032 active leases in the Gulf of America Region (approximately 11.03 million acres), 404 of which are actively producing (approximately 2.05 million acres). The last sale of acreage located in the Gulf of America Region took place on December 20, 2023, and offered 13,530 tracts (approximately 72.74 million acres), with 299 tracts (approximately 1.65 million acres) being awarded pursuant to the sale. The 10th OCS Program includes 3 lease sales covering acreage in the Gulf of America Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 7 lease sales in the Gulf of America Region.

Pacific Region

As of September 1, 2025, there were 30 active leases in the Pacific Region (approximately 152.57 thousand acres), all of which are actively producing leases. The last sale of acreage located in the Pacific Region took place on October 17, 1984, and offered 657 tracts (approximately 3.14 million acres) offshore Southern California, with 23 tracts (approximately 114.36 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Pacific Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 6 lease sales in the Pacific Region.

One Big Beautiful Bill Act

The 11th OCS Program will run concurrently with the lease sales planned under the One Big Beautiful Bill Act (OBBBA).  OBBBA mandates a minimum of 30 oil and gas lease sales covering the Gulf of America Region through March 15, 2040 (with no fewer than 1 sale in 2025, 2 sales annually for the years 2026 through 2039, and 1 sale in 2024) and 6 lease sales covering the Alaska Region through March 15, 2032 (with no fewer than 1 sale annually for the years 2026 through 2028 and 2030 through 2032). These legislatively mandated lease sales are separate from the discretionary lease sales proposed in the DPP for the 11th OCS Program.

Lease Sale Big Beautiful Gulf 1 (BBG1)

The 10th OCS Program was set to hold Lease Sale No. 262, which is the first of the 3 planned sales in the Gulf of America Region under that program. Lease Sale No. 262 has now been deferred, with the Big Beautiful Gulf 1 Oil & Gas Lease Sale (BBG1) replacing it as part of OBBBA.  BBG1 is set to occur on December 10, 2025, the first of the minimum 30 planned sales in that region.  Recently, on November 18, 2025, environmental groups filed suit against BOEM and DOI in U.S. District Court for the District of Columbia.  Allegations against the agencies include (i) the failure to conduct a necessary environmental review when finalizing BBG1, in violation of NEPA, and (ii) improper involvement of an agency official, in violation of the Administrative Procedure Act. The plaintiffs seek to vacate the Final Notice of Sale (FNOS) for BBG1, and to vacate or enjoin any leases that may be issued or actions taken pursuant to BBG1.  As of this post, BOEM is still moving forward with BBG1.

Lease Sale Big Beautiful Gulf 2 (BBG2)

On November 20, 2025, BOEM published its Proposed Notice of Sale (NOS) for Big Beautiful Gulf 2 Oil & Gas Lease Sale (BBG2), which proposes to offer for leasing approximately 15,000 unleased OCS blocks located in Gulf of America, all, regardless of depth, at the lowest allowable federal offshore royalty rate of 12.5%.  BBG2 is proposed to take place on March 11, 2026, and will be the second of the 30 minimum oil and gas lease sales in the Gulf of America Region called for under the OBBBA. Leases covering OCS blocks in depths less than 800 meters are to have primary terms of five years, while those covering blocks in depths of 800 meters or greater are to have primary terms of ten years.  Additionally, BBG2 will utilize the BOEM-2005 (February 2017) lease form, which includes updates to lease stipulations 1, 2, 3, and 10 contained in the FNOS for Lease Sale 254, with lease stipulations 4 through 9 being unchanged. Finally, the NOS for BBG2 calls for the FNOS to be published in the Federal Register at lease thirty days prior to the date of the opening of the bids.

For more information regarding the National OCS Oil and Gas Leasing Program and the 11th OCS Program, please visit https://www.boem.gov/oil-gas-energy/national-program/national-ocs-oil-and-gas-leasing-program.

For more information on BBG2, please visit https://www.boem.gov/oil-gas-energy/leasing/big-beautiful-gulf-2-bbg2-oil-gas-lease-sale

Blogs

DOI Issues Draft Proposed 2026-2031 National Outer Continental Shelf Oil and Gas Leasing Program: Sales Scheduled for Alaska, Gulf of America, and Pacific Regions

December 1, 20256 minute read

Featured Image


On November 24, 2025, the U.S. Department of Interior (DOI) published its Notice of Availability of the 1st Analysis and Proposal of the Draft Proposed Program (DPP) for the 11th National Outer Continental Shelf (OCS) Oil and Gas Leasing Program (11th OCS Program), opening up a statutorily required 60-day public review and comment period on the DPP in order to assist the Secretary of Interior in its determination of which areas to include in the final, approved program.  In furtherance of the ongoing implementation of President Trump’s Executive Order 14154, entitled “Unleashing American Energy,” the DPP (i) is the second of five steps in the Federal government’s process of developing a new five-year plan for holding offshore oil and gas lease sales on the Outer Continental Shelf (OCS), consistent with the Outer Continental Shelf Lands Act, 43 U.S.C. § 1331, et seq., and (ii) once approved, is expected to terminate and replace the 10th National OCS Oil and Gas Leasing Program (10th OCS Program) promulgated under the Biden administration, which is ongoing and currently set to expire on June 30, 2029.  As proposed, the DPP covers acreage in the Alaska, Gulf of America, and Pacific Regions of the OCS and aims to make more than 85% of the estimated technically recoverable OCS oil and gas resources available for sale during the five-year period following approval of the 11th OCS Program.  Pursuant to the DPP, “Inclusion of an area in [the DPP] is not a final indication that it will be included in the approved 11th [OCS] Program, or offered in a lease sale, because additional decision points remain to potentially reduce or completely remove an area or sale.”

Unlike prior National Leasing Programs, the Bureau of Ocean Energy Management (BOEM) plans to prepare an environmental analysis outside of the typical programmatic environmental impact statement under the National Environmental Policy Act (NEPA) for the 11th OCS Program (instead BOEM will prepare NEPA review on a lease basis pursuant to an environmental assessment, environmental impact statement, or determination of NEPA adequacy). Additionally, the 11th OCS Program would be the first implemented program to cover the areas within BOEM’s new jurisdictional limits, as revised by DOI on April 30, 2025, which increased the number of planning areas from 26 to 27, but decreased the total acreage offered from approximately 1.72 billion acres to 1.68 billion acres. As currently proposed, the DPP for the 11th OCS Program comprises 21 of the 27 the planning areas, consisting of 1.27 billion acres, and proposes the following lease sale schedule:

No.Sale YearOCS RegionProgram Area
12026AlaskaBeaufort Sea Program Area
22027PacificSouthern California Program Area
32027PacificCentral California Program Area
42027Gulf of AmericaGOA Program Area A
52027AlaskaCook Inlet Program Area
62028AlaskaChukchi Sea Program Area
72028Gulf of AmericaGOA Program Area A
82028AlaskaCook Inlet Program Area
92029PacificSouthern California Program Area
102029PacificNorthern California Program Area
112029PacificCentral California Program Area
122029Gulf of AmericaGOA Program Area A
132029Gulf of AmericaGOA Program Area B
142029AlaskaCook Inlet Program Area
152030AlaskaGulf of Alaska Program Area
162030AlaskaShumagin Program Area
172030AlaskaKodiak Program Area
182030Gulf of AmericaGOA Program Area B
192030Gulf of AmericaGOA Program Area A
202030AlaskaCook Inlet Program A
212030PacificSouthern California Program Area
222030AlaskaChukchi Sea Program Area
232030AlaskaBeaufort Sea Program Area
242030AlaskaHope Basin Program Area
252030AlaskaNorton Basin Program Area
262030AlaskaNavarin Basin Program Area
272030AlaskaSt. George Basin Program Area
282030AlaskaHigh Arctic Program Area
292031Gulf of AmericaGOA Program Area A
302031AlaskaCook Inlet Basin Program Area
312031AlaskaAleutian Basin Program Area
322031AlaskaAleutian Arc Program Area
332031AlaskaBowers Basin Program Area
342031AlaskaSt. Matthew-Hall Program Area

Notably, the DPP proposes leasing acreage in the Central, Northern, and Southern California Planning Areas, which have not been offered for lease in over forty years. The DPP also reflects the Secretary of Interior’s intent to (i) make available for leasing a newly created South-Central GOA Planning Area, designated on the table above, as GOA Program Area B, which is located in the southwestern portion of the current Eastern GOA Planning Area and, (ii) remove the remaining Eastern GOA Planning Area from further leasing under the 11th OCS Program.

Below is a comparison of the 11th OCS Program, as currently proposed, on the four OCS Regions versus the 10th OCS Program’s impact on these same regions:

Atlantic Region

As of September 1, 2025, there were no active leases in the Atlantic Region. The last sale of acreage located in the Atlantic Region took place on July 26, 1983, and offered 3,582 tracts (approximately 20.15 million acres) in the Southern Atlantic, with 11 tracts (approximately 62.62 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Atlantic Region.

The DPP for the 11th OCS Program, as currently proposed, does not plan to offer for sale any acreage in the Atlantic Region.

Alaska Region

As of September 1, 2025, there were 11 active leases in the Alaska Region (approximately 55.97 thousand acres), 3 of which are actively producing (approximately 10.42 thousand acres). The last sale of acreage located in the Alaska Region took place on December 30, 2022, and offered 193 tracts (approximately 958.20 thousand acres) in the Cook Inlet, with 1 tract (approximately 5.69 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Alaska Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 21 lease sales in the Alaska Region.

Gulf of America Region

As of September 1, 2025, there were 2,032 active leases in the Gulf of America Region (approximately 11.03 million acres), 404 of which are actively producing (approximately 2.05 million acres). The last sale of acreage located in the Gulf of America Region took place on December 20, 2023, and offered 13,530 tracts (approximately 72.74 million acres), with 299 tracts (approximately 1.65 million acres) being awarded pursuant to the sale. The 10th OCS Program includes 3 lease sales covering acreage in the Gulf of America Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 7 lease sales in the Gulf of America Region.

Pacific Region

As of September 1, 2025, there were 30 active leases in the Pacific Region (approximately 152.57 thousand acres), all of which are actively producing leases. The last sale of acreage located in the Pacific Region took place on October 17, 1984, and offered 657 tracts (approximately 3.14 million acres) offshore Southern California, with 23 tracts (approximately 114.36 thousand acres) being awarded pursuant to the sale. The 10th OCS Program does not include any planned lease sales in the Pacific Region.

The DPP for the 11th OCS Program, as currently proposed, plans to hold 6 lease sales in the Pacific Region.

One Big Beautiful Bill Act

The 11th OCS Program will run concurrently with the lease sales planned under the One Big Beautiful Bill Act (OBBBA).  OBBBA mandates a minimum of 30 oil and gas lease sales covering the Gulf of America Region through March 15, 2040 (with no fewer than 1 sale in 2025, 2 sales annually for the years 2026 through 2039, and 1 sale in 2024) and 6 lease sales covering the Alaska Region through March 15, 2032 (with no fewer than 1 sale annually for the years 2026 through 2028 and 2030 through 2032). These legislatively mandated lease sales are separate from the discretionary lease sales proposed in the DPP for the 11th OCS Program.

Lease Sale Big Beautiful Gulf 1 (BBG1)

The 10th OCS Program was set to hold Lease Sale No. 262, which is the first of the 3 planned sales in the Gulf of America Region under that program. Lease Sale No. 262 has now been deferred, with the Big Beautiful Gulf 1 Oil & Gas Lease Sale (BBG1) replacing it as part of OBBBA.  BBG1 is set to occur on December 10, 2025, the first of the minimum 30 planned sales in that region.  Recently, on November 18, 2025, environmental groups filed suit against BOEM and DOI in U.S. District Court for the District of Columbia.  Allegations against the agencies include (i) the failure to conduct a necessary environmental review when finalizing BBG1, in violation of NEPA, and (ii) improper involvement of an agency official, in violation of the Administrative Procedure Act. The plaintiffs seek to vacate the Final Notice of Sale (FNOS) for BBG1, and to vacate or enjoin any leases that may be issued or actions taken pursuant to BBG1.  As of this post, BOEM is still moving forward with BBG1.

Lease Sale Big Beautiful Gulf 2 (BBG2)

On November 20, 2025, BOEM published its Proposed Notice of Sale (NOS) for Big Beautiful Gulf 2 Oil & Gas Lease Sale (BBG2), which proposes to offer for leasing approximately 15,000 unleased OCS blocks located in Gulf of America, all, regardless of depth, at the lowest allowable federal offshore royalty rate of 12.5%.  BBG2 is proposed to take place on March 11, 2026, and will be the second of the 30 minimum oil and gas lease sales in the Gulf of America Region called for under the OBBBA. Leases covering OCS blocks in depths less than 800 meters are to have primary terms of five years, while those covering blocks in depths of 800 meters or greater are to have primary terms of ten years.  Additionally, BBG2 will utilize the BOEM-2005 (February 2017) lease form, which includes updates to lease stipulations 1, 2, 3, and 10 contained in the FNOS for Lease Sale 254, with lease stipulations 4 through 9 being unchanged. Finally, the NOS for BBG2 calls for the FNOS to be published in the Federal Register at lease thirty days prior to the date of the opening of the bids.

For more information regarding the National OCS Oil and Gas Leasing Program and the 11th OCS Program, please visit https://www.boem.gov/oil-gas-energy/national-program/national-ocs-oil-and-gas-leasing-program.

For more information on BBG2, please visit https://www.boem.gov/oil-gas-energy/leasing/big-beautiful-gulf-2-bbg2-oil-gas-lease-sale


Blogs

Environmental Groups Sue Over Gulf Lease Sale Without NEPA Review

November 26, 2025less than a minute

Featured Image
A recent ENERGYWIRE article examines a lawsuit filed by several environmental groups challenging the Trump administration’s plan to move forward with a large offshore oil and gas lease sale in the Gulf of America without first conducting an environmental review under the National Environmental Policy Act (NEPA). 
 
Liskow Shareholder Jana Grauberger provides context on why this sale stands out from prior ones, noting that it is “occurring outside the typical framework applicable to federal offshore oil and gas leasing.” She explains that NEPA is normally addressed both in BOEM’s five-year plan and again at the individual sale stage, making this deviation notable.
 
To read the full article, click here.

Blogs

Commonwealth LNG Update: LDCE Re-Issues LNG Permit with Revised Basis of Decision

November 26, 20253 minute read

Featured Image

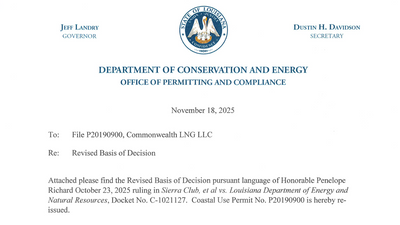
On November 18, 2025, the Louisiana Department of Conservation and Energy (LDCE) re-issued a Coastal Use Permit (CUP) with a revised Basis of Decision that incorporates environmental justice (EJ) and climate change assessments related to Commonwealth’s proposed LNG facility. LDCE is re-issuing the CUP following a Louisiana district court’s vacatur of the prior CUP for the Commonwealth LNG facility based on the court’s finding that LDCE failed to analyze EJ or climate change impacts.

LDCE stated in the revised Basis of Decision that it is not conceding the correctness of the district court judgment or forgoing the right to challenge the judgment. Rather, LDCE determined that it is in the best interest of the State to not delay the matter further and is thus addressing the issues raised by the district court, namely the “facility’s impact on climate-related change in the coastal zone, if any, in conjunction with the other LNG facilities in the area, as well as [EJ] issues.” 

At the outset of its own analysis, LDCE noted that the administrative record for the matter already contains a discussion on EJ and climate change impacts, specifically referencing the Federal Energy Regulatory Commission’s (FERC) Final Environmental Impact Statement (FEIS) and the Louisiana Department of Environmental Quality’s (LDEQ) air permitting basis for decision. 

Environmental Justice

LDCE initially provided that “re-creation of the EJ analysis undertaken by both the FERC and LDEQ is no longer possible as the [EJ] tools they utilized, such as EPA’s EJ Screen, are no longer available” following the issuance of a President Trump Executive Order.

Nonetheless, LDCE extensively quoted from the FERC FEIS that outlined potential adverse environmental impacts on EJ communities, including impacts on wetlands, social patterns, commercial and recreational fishing, and the cumulative impacts related to each. LDCE stated that it independently reviewed the EJ analysis and agrees with the FEIS’s determinations, concluding that the project’s environmental impacts on EJ communities will be less than significant and will not impose disproportionate adverse effects based on race, color, national origin, or income.

Climate Change

LDCE also quoted from the FERC FEIS and LDEQ basis for decision’s discussion on the potential climate change-related impacts, including flooding and storm impacts, associated with the proposed project. LDCE again indicated that it independently reviewed climate change impacts and agrees with both agencies’ analyses. After this analysis, LDCE stated that “the benefits of this project outweigh the costs to the community” after considering the facility’s potential impact on climate-related change in the coastal zone, in conjunction with that of the other LNG facilities in the area.

For more information, please contact Liskow attorneys Greg Johnson, Clare Bienvenu, Emily von Qualen, and Colin North, and visit Liskow’s The Louisiana Industrial Insights Hub to follow along to stay up-to-date on Public Trust Duty developments.


Without conceding the correctness of the trial court judgment, nor in anyway limiting the OCM’s rights to challenge the trial court’s conclusion, and reserving all possible defenses and legal arguments in this matter and others, OCM determines that it being in the best interest of the State to not delay this matter further does here provide additional consideration of the record to specifically analyze “the facility’s impact on climate-related change in the coastal zone, if any, in conjunction with the other LNG facilities in the area, as well as environmental justice issues.”

files.passle.net/…

Blogs

Fifth Circuit Rules Contract to Repair Offshore Oil & Gas Platform Not a Maritime Contract

November 26, 20254 minute read

In another recent decision, Genesis Energy, L.P. v. Danos, L.L.C., 152 F.4th 648 (5th Cir. 2025), the United States Fifth Circuit Court of Appeals found yet again that a contract to repair an offshore oil & gas platform was governed by Louisiana law pursuant to the Outer Continental Shelf Lands Act, rather than maritime law. In clarifying the maritime contract test set forth in In re Larry Doiron, Inc., 879 F.3d 568, 576 (5th Cir. 2018) (en banc), the Court instructed that when a contract involves platform (not vessel) repair, the proper focus is on the “use” of the vessel for work, and “whether the contract calls for substantial work to be performed from a vessel.” Even though a vessel was used for ancillary functions that may have facilitated the platform repairs, Doiron calls for a close nexus between the vessel and the project’s work. Accordingly, the defense and indemnity provision in the underlying Master Services Agreement was invalid under the Louisiana Oilfield Anti-Indemnity Act (“LOAIA”).

The Fifth Circuit’s ruling provides additional insight and clarity on how the Court views contracts relating to offshore oil and gas platforms, particularly when vessel involvement is only “ancillary” to the work being performed (i.e. repair of a platform).  A detailed discussion of the case and the Court’s analysis is discussed in the sections below.

Background and Lower Court Ruling

In August 2020, Hurricane Laura damaged the Genesis Garden Banks 72, an offshore platform owned by Genesis Energy, LP and located on the Outer Continental Shelf off the coast of Louisiana.  Genesis’ subsidiary contracted with Danos, LLC, to conduct repairs, entering into an oral work order that was memorialized by a written “Job Plan.”  To facilitate this project, Genesis chartered the 240-foot offshore supply vessel named Cheramie Botruc #41 (the “Vessel”), which was owned by L&M Botruc Rental, LLC.

In November 2020, Maximo Sequera, a Danos employee, fell from a personnel basket while transferring from the platform to the Vessel, sustaining injuries.  Sequera sued Danos, Genesis, and Botruc Rental in Texas state court, and Danos removed the action to the Southern District of Texas.  Genesis then filed a crossclaim against Danos seeking defense and indemnity in connection with the Master Services Agreement executed by Genesis’ and Danos’ predecessors-in-interest in 2008.  Danos moved for summary judgment, contending that Genesis’ crossclaim should be dismissed because the agreement was not maritime in nature and that Louisiana state law applied, invalidating the defense and indemnity provision.  Genesis also moved for summary judgment, asserting that Danos was contractually obligated to provide defense and indemnity to Genesis. 

The Southern District of Texas agreed with Danos, holding that the parties’ contract was not maritime in nature and that the LOAIA applied, barring the enforceability of the defense and indemnity provision.  The Court reasoned that “the terms of the Danos/Genesis contract and the expectations of the parties under it don’t clearly establish that they anticipated platform-repair work under the contract to involve a substantial role for the vessel.” The Court granted Danos’ cross-motion for summary judgment, denied Genesis’ motion for summary judgment, and dismissed Genesis’ crossclaim with prejudice.  Genesis appealed.    

The Fifth Circuit Appeal

On appeal, the Fifth Circuit first examined the three contracts relevant to the platform repairs: the Master Services Agreement, the “Job Plan,” and the Botruc Rental bid document.  For example, the Job Plan had a stated objective to “[m]ake [the] platform safe for riser de-oil operations and drain the CHOPS pig launcher and receiver,” and its Scope of Work listed steps to complete the project but made no mention of the Vessel.  While the “Detailed Procedure” section listed additional steps and made one reference to the Vessel, it also provided that “crews will live on the vessel and transfer to the platform daily via man basket.” 

Similarly, the bid document only provided for transporting the crew and providing meals and lodging.  Citing its previous decision in Earnest v. Palfinger Marine USA, Inc., 90 F.4th 804, 810 (5th Cir. 2024), the Fifth Circuit concluded that all three agreements failed to establish a “direct and substantial link between the contract and the operation of the ship, its navigation, or its management afloat.”  The Court concluded that the agreements “establish at most that the Vessel would transfer and house the crew, but we have previously dismissed those uses as insufficient to establish a vessel’s ‘substantial role.’”   

The Court next examined evidence of the parties’ expectations surrounding the platform repair project to determine if the Vessel had been expected to play a substantial role.   Genesis relied on two declarations from Danos and Genesis employees as evidence of the parties’ expectations that “the continuous use of the [Vessel] was necessary for Danos to complete its repair work.”  The declarations stated that the parties knew that the Vessel would be used as living quarters and a mess hall and that it would remain alongside the Platform for the duration of repairs.  

The Court held that “the declarations’ description of the Vessel as ‘necessary’ to the work is insufficient standing alone, because vessels are often necessary for offshore work.”  The Court pointed out that in its post-Doiron decisions, it had instead focused on whether the vessel at issue was “expected to directly aid the completion of the project.”  See, e.g. In re Crescent Energy Servs., L.L.C., 896 F.3d 350, 360 (5th Cir. 2018). Because “the parties anticipated that the Vessel would only house equipment that would later be transferred to the platform, where it would facilitate repairs”, the Vessel’s role was considered insubstantial under Doiron. 

Regarding the Vessel’s ancillary functions, the Court noted that it had previously held that housing is merely an “incidental” role for a vessel, while a vessel’s use for “transportation to and from the job site” is to be ignored.  The Court clarified that “[w]hile these ancillary functions may have facilitated the Platform repairs, Doiron calls for a closer nexus between the Vessel and the project’s work than these functions have.”  The Fifth Circuit thus affirmed the district court, holding that the parties’ agreement was not maritime in nature and that the LOAIA applied, invalidating Danos’ defense and indemnity obligations to Genesis.

For more information, contact Liskow attorneys Nicolette Kraska and Alex Baynham and visit Liskow’s Maritime Litigation & Casualty Response practice page.


Blogs

Tax Court Holds Policy Loan Discharge on Terminated Life Insurance Contracts Creates Taxable Income

November 25, 20253 minute read

Featured Image

In Fugler v. Commissioner, T.C. Summ. Op. 2025-10 (Nov. 17, 2025), the U.S. Tax Court addressed the tax consequences of terminating whole life insurance policies with outstanding policy loans. The decision reinforces long-standing principles governing the taxation of policy surrenders and loan discharges, and it illustrates the limited scope of defenses available when taxpayers fail to report amounts shown on Forms 1099-R.

The taxpayer had purchased two whole life insurance policies on the lives of his children. Over the years, he borrowed against the policies, taking out lump-sum loans and subsequently borrowing additional amounts to pay ongoing premiums. By 2018, the outstanding loan balances on both policies exceeded the cash surrender value. When the taxpayer surrendered the policies, the insurer issued a Form 1099-R reporting gross distributions that included both cash paid to the taxpayer and the discharged loan balances. The form also reported taxable amounts resulting from the termination of the policies with outstanding indebtedness. The taxpayer did not include any portion of the distribution in income on his 2018 return, prompting the IRS to issue a notice of deficiency along with an accuracy-related penalty.

In the ensuing Tax Court litigation, the taxpayer advanced several arguments, all of which the court rejected. First, he contended that the income resulting from the policy terminations was properly reportable in a different tax year. The court disagreed, holding that the taxable event occurred in 2018, the year both policies were surrendered and the loan balances were extinguished. Consistent with established precedent, the court explained that when a life insurance contract is terminated and outstanding loans are discharged, the discharged indebtedness is treated as part of the policy proceeds and included in gross income in the year of termination to the extent it exceeds the taxpayer’s investment in the contract.

The taxpayer next argued that he was entitled to deduct the interest on the policy loans as business interest expense. The court found no evidence that the loans were used for a trade or business and noted that the taxpayer had provided no documentation connecting any of the borrowed amounts to business activities. Without substantiation or a valid business purpose, the court concluded that the taxpayer was not entitled to any deduction for interest paid or accrued on the policy loans.

Finally, the taxpayer sought innocent spouse relief under section 6015(f). Although the Commissioner conceded that equitable relief was available to the taxpayer’s spouse, the court held that the taxpayer himself did not qualify. Section 6015(f) provides relief only to spouses seeking protection from joint liability due to the other spouse’s actions, and the taxpayer failed to demonstrate that he met the statutory and regulatory criteria. Because he was the spouse responsible for the unreported income and erroneous positions taken on the joint return, he was not eligible for relief.

Having rejected each of the taxpayer’s arguments, the court sustained both the deficiency and the accuracy-related penalty under section 6662. The opinion underscores the importance of properly reporting distributions reflected on Forms 1099-R, including taxable amounts attributable to the discharge of policy loans at surrender. It also highlights the narrow circumstances under which taxpayers may claim business-interest deductions or obtain innocent spouse relief when they themselves controlled the transactions at issue.

Taxpayers with life insurance policies encumbered by loans should be aware of the potential income tax consequences upon policy surrender or lapse. When loan balances exceed the taxpayer’s basis in the policies, termination will often result in taxable income, even if no cash is actually received. If you have questions about this update or require estate and tax planning advice, please contact Liskow attorneys Leon Rittenberg III, John Rouchell, Caroline Lafourcade, and Kevin Naccari and visit our Tax practice page. 

Blogs

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 12
  • Page 13
  • Page 14
  • Page 15
  • Page 16
  • Interim pages omitted …
  • Page 188
  • Go to Next Page »

Primary Sidebar

Recent Posts

  • IRS Permits Entity Classification Change Following Significant Ownership Change
  • A Spirited Debate: Supreme Court to Review Federal Ban on Home Distilling
  • “Credit or Debit?”: IRS Issued Final Regulations Simplifying Tax Payments by Credit or Debit Card
  • Considering an ESOP? New Law Reduces Valuation Risk
  • EPA Finalizes Rule Clarifying “Applicable Requirements” Under Title V Program

Categories

  • Blogs
  • Events
  • Insights
  • News
Liskow & Lewis, APLC
Arrow Icon

future-focused

  • Baton Rouge
  • Houston
  • Lafayette
  • New Orleans
  • New York City
  • New Bedford
  • © 2026 Liskow & Lewis, APLC
  • Sitemap
  • Disclaimer
  • Employee Login
Site by
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
Cookie SettingsAccept All
Manage consent

Privacy Overview

This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary
Always Enabled
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
CookieDurationDescription
cookielawinfo-checkbox-analytics11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional11 monthsThe cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy11 monthsThe cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytics
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Others
Other uncategorized cookies are those that are being analyzed and have not been classified into a category as yet.
SAVE & ACCEPT
  • Team
  • Practices
  • Insights
  • Blogs
  • Offices
  • Pro Bono
  • About Us
  • Careers
  • DEI
  • The Energy Law Blog
  • Gulf Coast Business Law Blog
  • The Maritime Law Blog